Understanding the Bay Area Housing Market in 2026
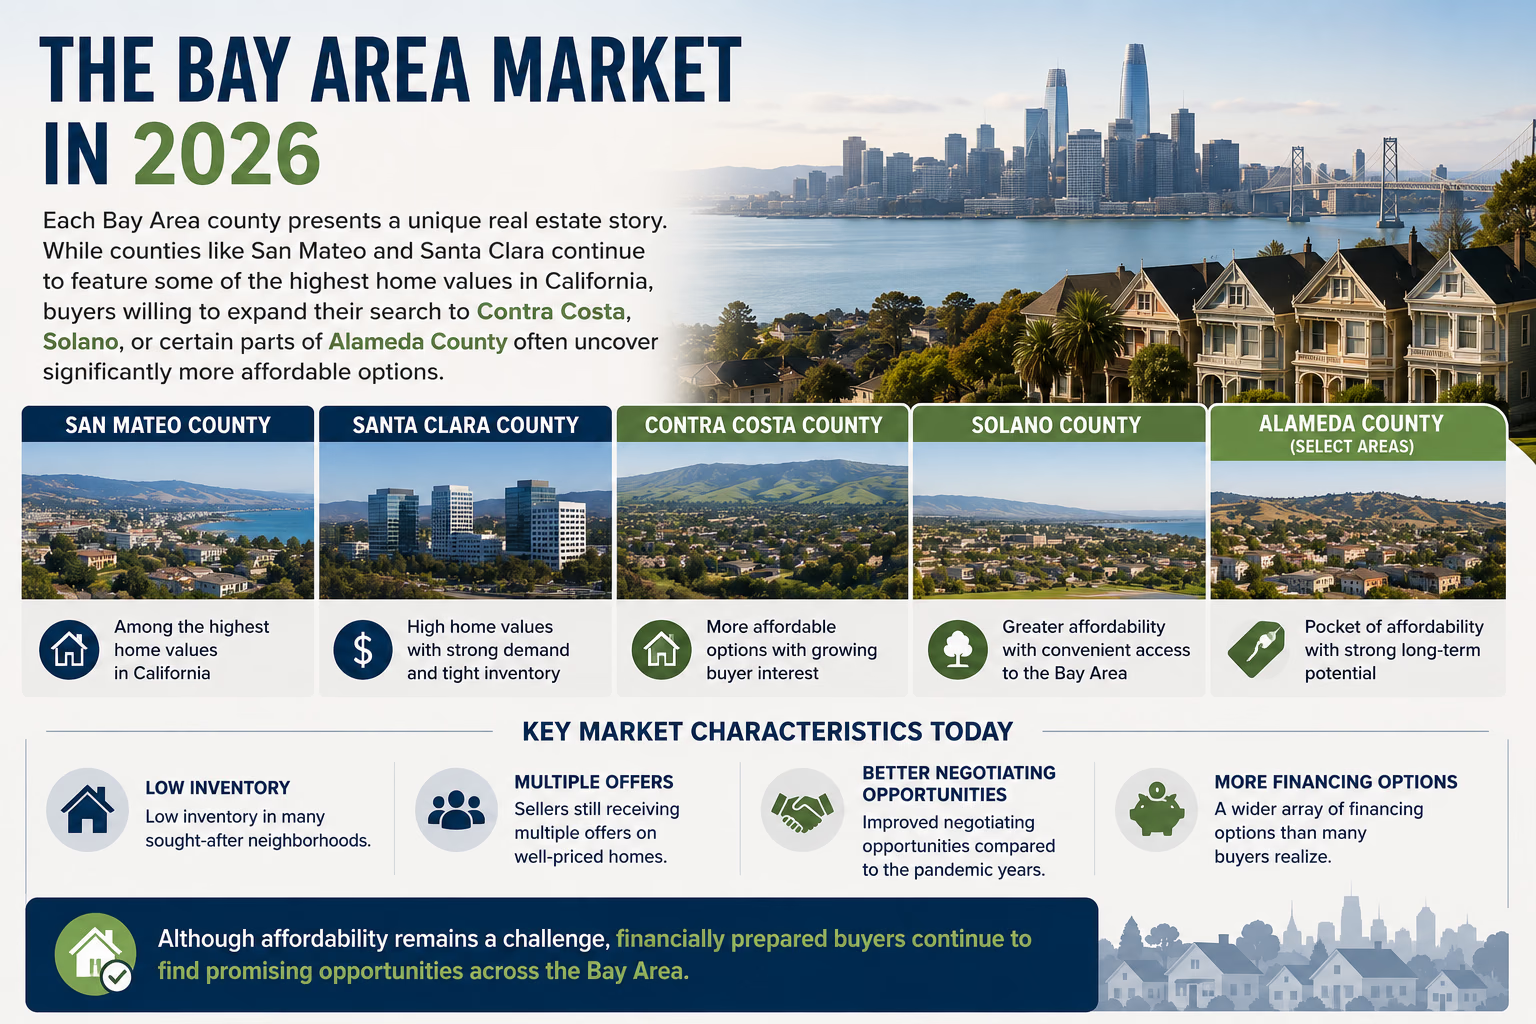
Each Bay Area county presents a unique real estate story. While counties like San Mateo and Santa Clara continue to feature some of the highest home values in California, buyers willing to expand their search to Contra Costa, Solano, or certain parts of Alameda County often uncover significantly more affordable options.Key market characteristics today include low inventory in many sought-after neighborhoods, sellers still receiving multiple offers on well-priced homes, improved negotiating opportunities compared to the pandemic years, and a wider array of financing options than many buyers realize.Although affordability remains a challenge, financially prepared buyers continue to find promising opportunities.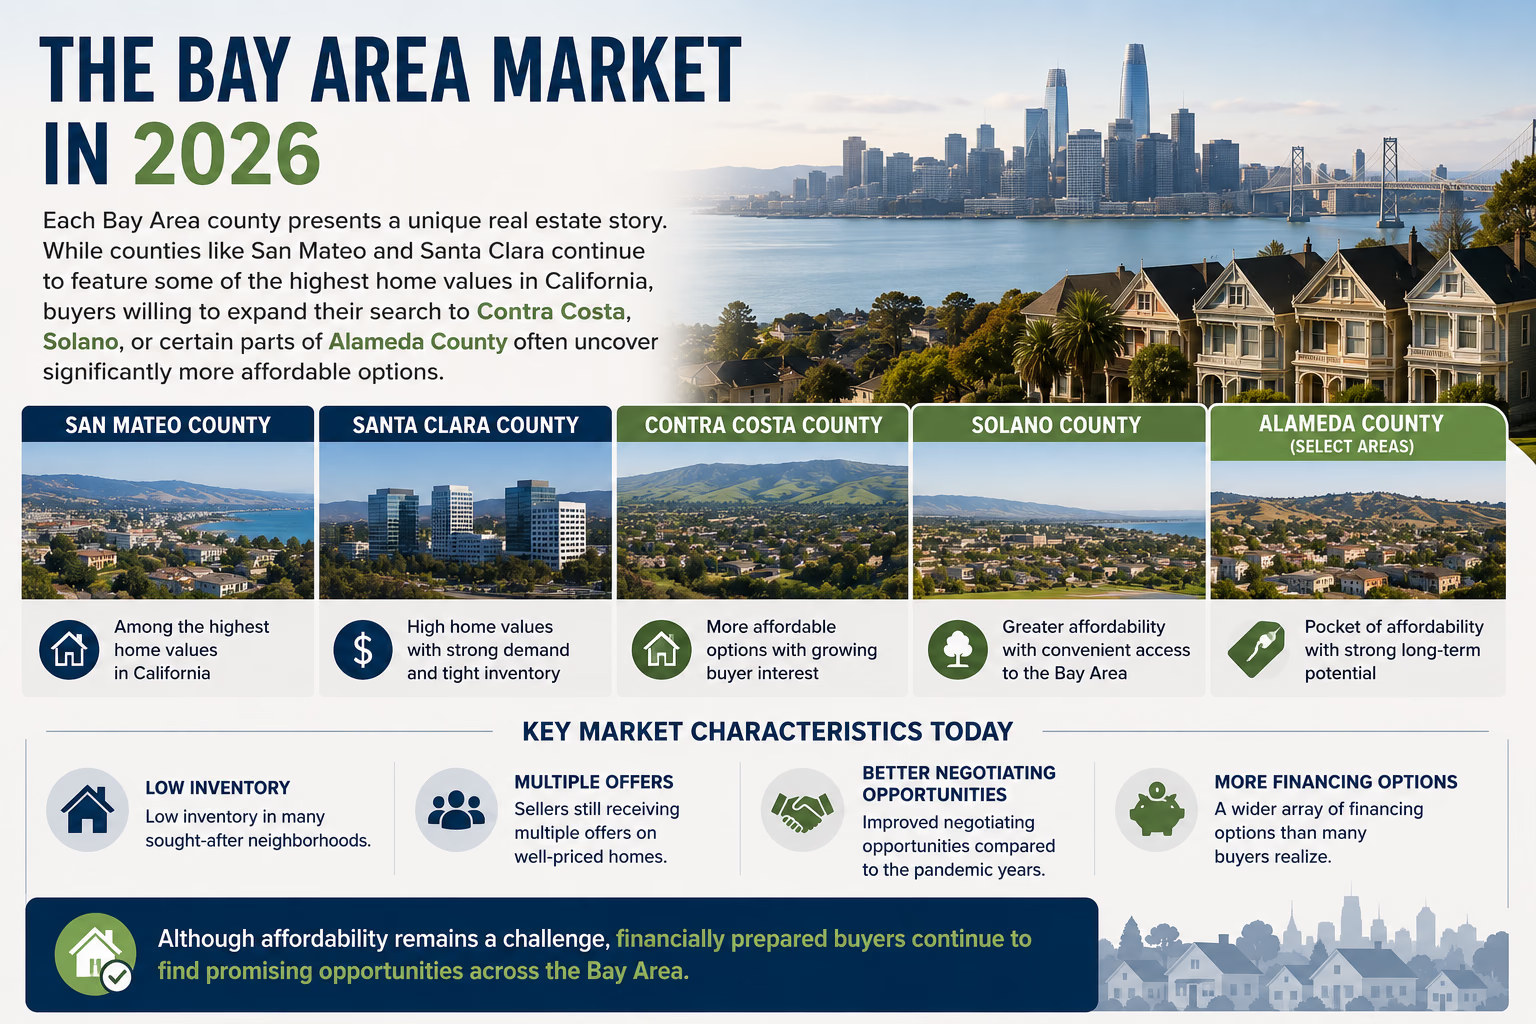
Where First-Time Buyers Can Still Find Value
One common mistake is restricting your home search to a single city before fully understanding what your budget can realistically afford. Broadening your horizons can reveal attainable neighborhoods that meet your needs.Contra Costa County
Communities such as Antioch, Pittsburg, Oakley, Brentwood, Martinez, Concord, Bay Point, and parts of Richmond continue to attract first-time buyers seeking more space without the Silicon Valley price tag. These areas offer single-family homes, newer developments, convenient BART access, and growing local amenities.Solano County
Fairfield, Vacaville, and Vallejo remain some of the most affordable entry points into Bay Area homeownership. For buyers who commute only a few days per week, Solano County is a compelling option worth serious consideration.Alameda County
Buyers interested in condos or townhomes may find excellent opportunities in Hayward, San Leandro, and parts of Oakland. These markets offer better affordability while preserving convenient access to major employment centers.You Don't Need 20% Down to Buy
A major myth in real estate is that you must have a 20% down payment. Many qualified buyers purchase homes with much less. Depending on your circumstances, you may qualify for:- Conventional loans with as little as 3% down
- FHA loans requiring 3.5% down
- VA loans with zero down for eligible veterans
- California down payment assistance programs
- Local grants and special funding opportunities
California Down Payment Assistance Programs
California offers a variety of programs designed to help first-time buyers tackle one of the biggest hurdles: saving enough cash for a down payment. These programs may assist with down payments, closing costs, deferred-payment second mortgages, or shared appreciation arrangements.Since eligibility, funding availability, and income limits can change frequently throughout the year, working with a lender familiar with these programs can make a significant difference in your buying power.How Much Income Do You Really Need to Buy?
There is no one-size-fits-all income requirement. Your purchasing power depends on multiple factors, including monthly income, existing debts, credit score, down payment size, property taxes, homeowners insurance, and any homeowners association dues.Two buyers earning the same salary may qualify for very different home prices depending on their financial profiles. For this reason, online mortgage calculators often provide only rough estimates.Five Tips to Give You a Competitive Advantage
1. Get Pre-Approved Before You Shop
Homes in the Bay Area often sell fast. A strong pre-approval letter lets you make an offer immediately without scrambling for paperwork, giving you a clear advantage.2. Expand Your Search Area
Sometimes driving 20 to 30 minutes further can open up many more affordable options and increase your chances of finding the right home.3. Keep Your Credit Healthy
Avoid opening new credit cards, financing vehicles, or making large purchases before closing. Even small changes can impact your mortgage qualification.4. Think Long-Term
Your first home doesn’t have to be your forever home. Many buyers purchase a home that fits their current needs while building equity for future moves.5. Understand All Your Loan Options
The lowest interest rate isn’t always the best loan. Different programs offer unique advantages depending on your goals, savings, and long-term plans.