Understanding the Sacramento Short Sale Process
A short sale occurs when your home sells for less than the amount owed on your mortgage, and your lender agrees to accept the proceeds. The lender’s approval depends on various factors, including your financial hardship, the property’s market value, and the proposed sale price. Unlike a standard sale, the lender acts as a decision-maker, reviewing your entire financial situation and market conditions before approving the transaction.Preparation is crucial. Starting early helps reduce delays, especially since short sales can involve multiple lienholders, complex documentation, and lender negotiations. Below is a comprehensive checklist to guide you through the preparation and approval process.Sacramento Short Sale Checklist: Documents to Gather
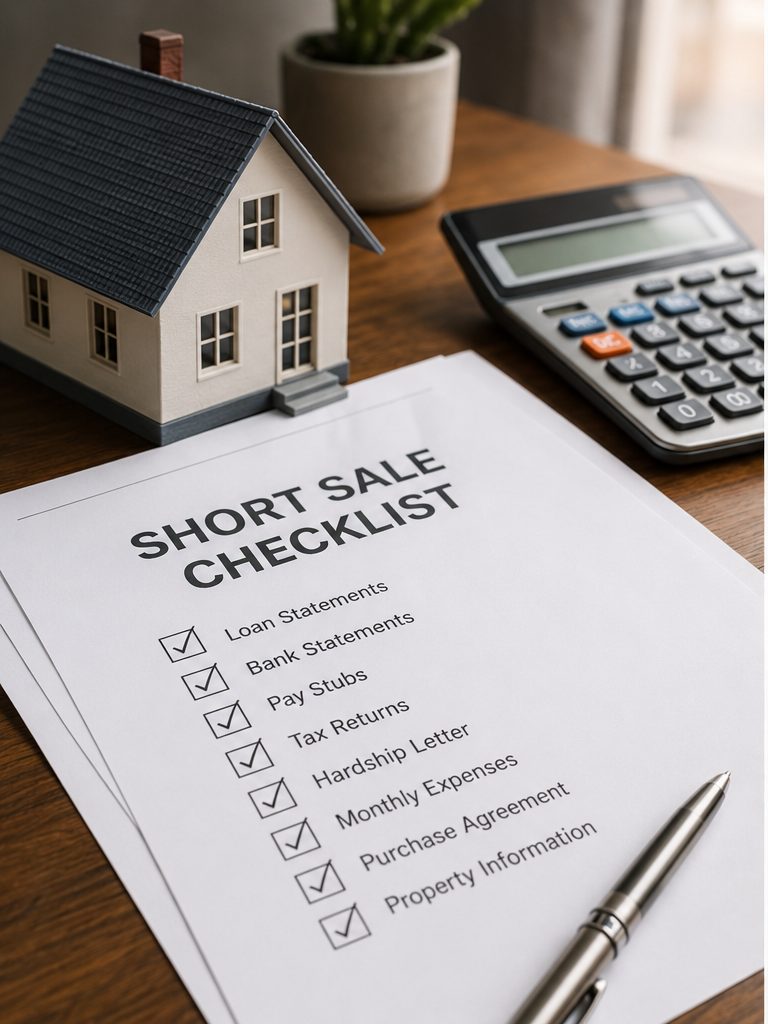
Every lender and loan servicer may have slightly different requirements, but generally, your short-sale package will include the following documentation:- Recent mortgage statements showing your current balances
- Bank statements
- Proof of income, such as pay stubs and W-2 forms
- Federal tax returns for the past two years
- Documentation of other income sources
- Monthly expense records
- Financial statements detailing assets and liabilities
- A hardship letter explaining your financial situation
- Purchase contract from the buyer
- Listing agreement with your real estate agent
- Preliminary settlement statement
- Required property disclosures
- Information about any additional liens or judgments
- Homeowners Association (HOA) documents if applicable
- Repair estimates or inspection reports
- Any lender-specific forms or requests
Step 1: Identify All Liens and Loans on Your Sacramento Property
Begin by determining every loan or lien attached to your home. This may include a first mortgage, second mortgage, Home Equity Line of Credit (HELOC), unpaid property taxes, HOA dues, or judgment liens. The presence of multiple lienholders adds complexity because all parties may need to approve the short sale.If you’re unsure about liens on your property, your real estate agent and title company can help identify these issues early, allowing you to address them proactively.Step 2: Determine Your Home’s Current Market Value with Neighborhood Comps
Establishing a realistic market value is essential. Your real estate agent will prepare a Comparative Market Analysis (CMA) that considers recent closed sales, current listings, and the condition of your property. Key factors include:- Square footage and lot size
- Number of bedrooms and bathrooms
- Renovations and property condition
- Garage and parking availability
- Neighborhood trends and walkability
- Proximity to major redevelopment projects, such as the former Kings arena site
Step 3: Write a Clear Financial Hardship Letter
Your lender will typically require a hardship letter explaining why you cannot maintain your mortgage payments. Be honest and specific about your situation. Common reasons include:- Job loss or reduced income
- Divorce or family separation
- Relocation for work
- Business setbacks
- Unexpected medical or other expenses
- Changes in household finances
Step 4: List Your Property with a Strategic Pricing and Marketing Plan
Once you decide to pursue a short sale, your agent will help you price and market your home. Pricing is critical to attract qualified buyers while aligning with lender expectations. Overpricing can result in low buyer interest and longer market time, increasing foreclosure risk. Conversely, pricing too low may create valuation discrepancies with the lender.A balanced pricing strategy considers the current Sacramento market, comparable sales, and your home’s condition to maximize buyer interest and lender approval chances.Step 5: Receive an Offer and Submit the Short Sale Package to the Lender
After receiving an offer, your agent will compile the short sale package to submit to the lender. This package typically includes:- Signed purchase agreement
- Buyer’s financial qualifications or proof of funds
- Estimated settlement statement
- Listing history and marketing activity
- Comparative market analysis supporting the price
- Property photos and repair documentation
- Your financial documentation and hardship letter
Step 6: Lender Review and Approval – What to Expect
This stage often requires the most patience. The lender will review all submitted documents, evaluating:- Your financial hardship and ability to pay
- Outstanding mortgage and lien balances
- Current market value and condition of the property
- Purchase price and buyer qualifications
- Closing costs and expected recovery amount
- Other liens and obligations
How Long Does a Sacramento Short Sale Take?
There is no fixed timeline. A straightforward short sale with complete documentation and a cooperative lender may close in as little as 6 to 8 weeks. However, complications such as multiple liens, valuation disputes, buyer financing issues, or foreclosure deadlines can extend the process to several months.If you’ve received a Notice of Default or Notice of Sale, acting quickly and maintaining communication with your lender is essential. Consulting a HUD-approved housing counselor or legal expert may also provide valuable guidance.How Sacramento Redevelopment Projects Impact Neighborhood Comps
Sacramento’s ongoing redevelopment projects, such as the transformation of the former Kings arena site north of downtown, influence neighborhood dynamics. These large-scale projects can affect buyer demand, neighborhood desirability, walkability, and local amenities.However, redevelopment does not automatically translate into higher home values for short sales. Lenders require current market evidence, not future projections, when evaluating your property’s worth.To assess redevelopment’s impact, consider factors including:- Recent comparable sales in the area
- Active listings and buyer interest
- Days on market and sale-to-list-price ratios
- Investor activity and multiple-offer situations
- Current buyer willingness to pay a premium
Selecting Quality Comparable Sales Matters
Sacramento consists of diverse neighborhoods and micro-markets. Properties just a few miles apart may attract different buyers and have varying values. When supporting your short sale price, your agent should choose comps that closely resemble your home in terms of:- Neighborhood and school district
- Distance from your property
- Size, age, and condition
- Renovations and upgrades
- Garage and parking availability
- Layout and amenities
- Proximity to redevelopment projects
- Recent buyer activity
Addressing Common Short Sale Challenges
One frequent challenge arises when the lender’s valuation exceeds the buyer’s offer. For example, if your mortgage balance is $525,000 but the lender values your home at $440,000 and the buyer offers $425,000, the lender may hesitate to approve the sale.Your agent can help by providing detailed documentation such as:- Recent comparable sales and active listings
- Photographs showing property condition
- Inspection and contractor repair estimates
- Evidence of deferred maintenance
- Market-time data and buyer interest metrics
- Neighborhood-specific market trends
Avoid These 10 Sacramento Short Sale Mistakes
- Waiting too long to explore options
- Ignoring lender correspondence or requests
- Submitting incomplete paperwork
- Overpricing your home
- Choosing weak or irrelevant comparable sales
- Assuming redevelopment guarantees higher value
- Overlooking additional liens or mortgages
- Believing lender approval is automatic
- Failing to address foreclosure deadlines proactively
- Delaying professional help until the last minute