Albany Measure S: The Transfer-Tax Tier That Can Change a Seller’s Net

Albany Measure S: The Transfer-Tax Tier That Can Change a Seller’s Net
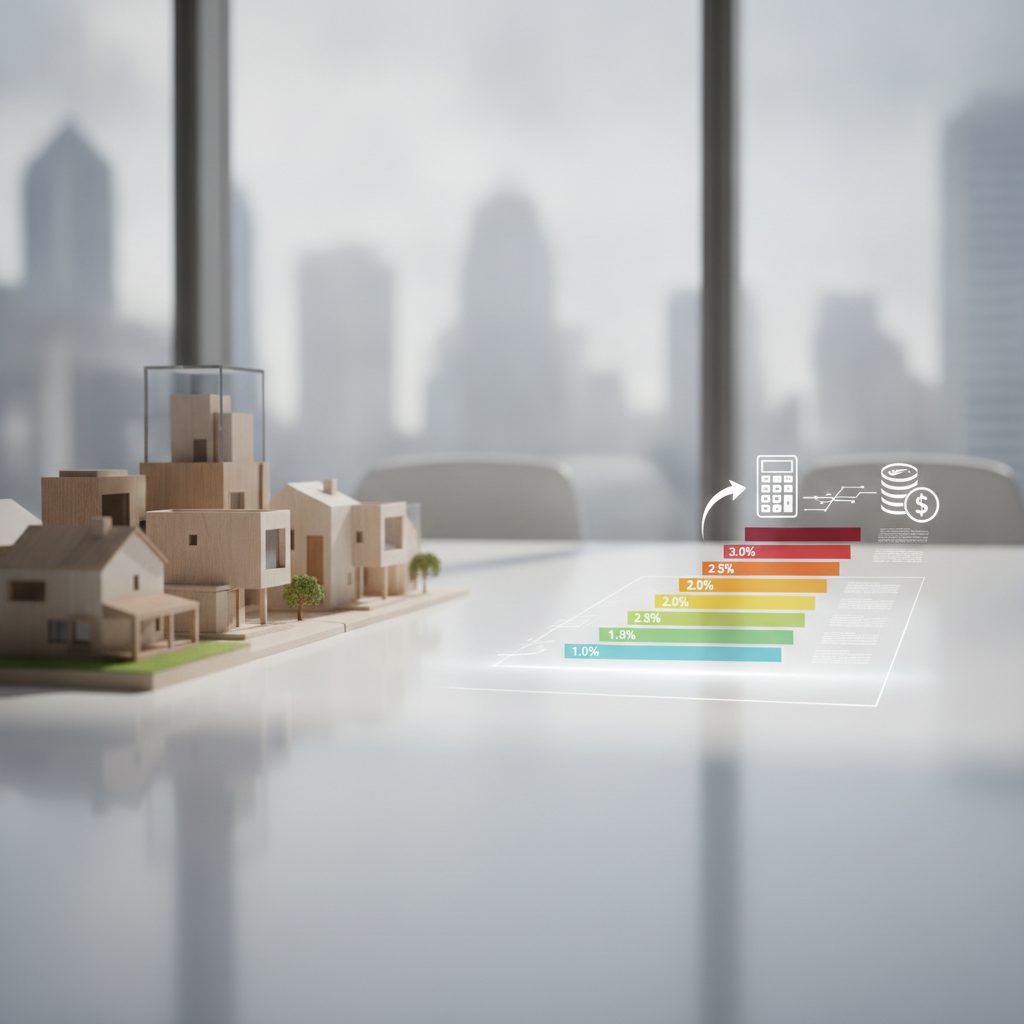
As of October 24, 2026, Albany Measure S is a proposal on the November 3 ballot—not current law. It would replace Albany’s flat 1.5% city real property transfer tax with five rates ranging from 1.0% to 3.0%.The detail that matters most for a seller’s net sheet is not simply the top rate. Under the proposal, the applicable rate would be selected from annually recalculated sale-price tiers and applied to the entire value transferred, not just the dollars above a threshold.My view: this is exactly the kind of rule that deserves a property-specific calculation before anyone changes a listing price, moving date, or downsizing plan. A headline about “lower” or “higher” taxes is not enough.WHAT MEASURE S PROPOSESAlbany currently charges $15 per $1,000 of transferred value, equal to 1.5%. Measure S would create five rates:• 1.0% for transactions in the lowest 25% of Albany transfer values• 1.5% for the 25th to 50th percentiles• 2.0% for the 50th to 75th percentiles• 2.5% for the 75th to 90th percentiles• 3.0% for the highest 10%The dollar cutoffs would be recalculated annually from transactions recorded by the Alameda County Assessor during the 12 months preceding September 1 of the prior year, then rounded to the nearest $100,000. The city’s July 20 presentation used 2024–25 data to illustrate cutoffs near $950,000, $1.375 million, $1.79 million, and $2.3 million. Those figures are examples, not permanent brackets.City of Albany Measure S page and official documents:https://www.albanyca.gov/Government/Election-Information/Ballot-Measures-for-General-Municipal-Election-2026City presentation with the five-tier example:https://www.albanyca.gov/files/assets/city/v/1/city-clerk/documents/elections/2026-election/ballot-measures/real-property-transfer-tax-presentation-slides-2026.07.20.pdfTHE WHOLE-PRICE EFFECTThe selected rate would apply to the full transaction value. In the city’s example, a sale below the illustrative $950,000 first-tier cutoff would be taxed at 1.0%, while a sale in the next tier would be taxed at 1.5% on the entire price. The same structure continues through the higher tiers.That creates a practical “cliff” near each annual boundary. Sellers should not assume that a slightly higher contract price always produces the same increase in net proceeds. The correct comparison is the final price minus the applicable transfer tax and all other transaction costs.Albany Scanner’s October 16, 2026 report explains the proposed tiers, the annual recalculation, and the whole-price application:https://www.albanyscanner.com/2026/10/16/elections/albany-measure-s-property-transfer-tax-explainer/The city estimates the measure would generate about $1 million in additional annual general-fund revenue. Because it is a general tax, the revenue would not be restricted to one specific program. Measure S requires a simple majority. If approved, the new structure would take effect January 1, 2027.WHO PAYS AT CLOSING?Albany’s municipal code makes buyers and sellers jointly responsible for the transfer tax, while the purchase contract can allocate the cost between them. That means the tax is not just a seller-side arithmetic exercise. It can affect price negotiations, credits, and how the parties divide closing expenses.Do not confuse this one-time city transfer tax with annual property tax. It is also separate from capital-gains tax and from Proposition 19 base-year-value portability.A DOWNSIZING CHECKLISTFor a longtime Albany homeowner considering a smaller home, I would separate the decision into four columns:1. Sale proceeds: estimated market value based on current, hyperlocal comparable sales—not Zillow or Redfin alone.2. One-time sale costs: the city transfer tax in effect on the closing date, brokerage compensation, inspections, repairs, staging, escrow, and title costs.3. Replacement-home costs: purchase price, HOA dues if any, insurance, maintenance, utilities, and financing.4. Ongoing property tax: whether Proposition 19 base-year-value transfer may apply.California’s State Board of Equalization says qualifying homeowners age 55 or older may transfer a base-year value to a replacement principal residence anywhere in California, subject to ownership, principal-residence, timing, value, claim, and other requirements. The replacement must generally be purchased or newly constructed within two years of the original home’s sale. A higher-value replacement can add an amount to the transferred taxable value. This is property-tax assessed-value portability, not a capital-gains exclusion.Official Proposition 19 guidance:https://www.boe.ca.gov/prop19/SHOULD A SELLER WAIT?No one should assume that waiting guarantees a better tax result. The election outcome is unknown as of October 24. If Measure S passes, the tier thresholds would move annually. Meanwhile, buyer demand, mortgage rates, inventory, property condition, insurance, and the replacement-home market can change.My advice is to model at least two net sheets: one under today’s flat 1.5% rate and one under the proposed tier most likely to apply at the expected closing date. Then compare the tax difference with the lifestyle and financial reasons for moving.Life is short. A home that fit for 20 years may not fit now. But a good downsizing decision is not made from urgency or fear; it is made by separating one-time costs from long-term costs and using current, property-specific numbers.Oliver Davis is a French-American real estate agent with Fast Real Estate / eXp Realty, fluent in English and French, serving Albany, Berkeley, Oakland, and the East Bay. DRE #01996487.
#AlbanyMeasureTransfer#Albany#Measure#Transfer#Change#Seller#ExplainProposedGraduated#Explain#Proposed#Graduated#Structure#Affect