
What's happening in Alameda right now?
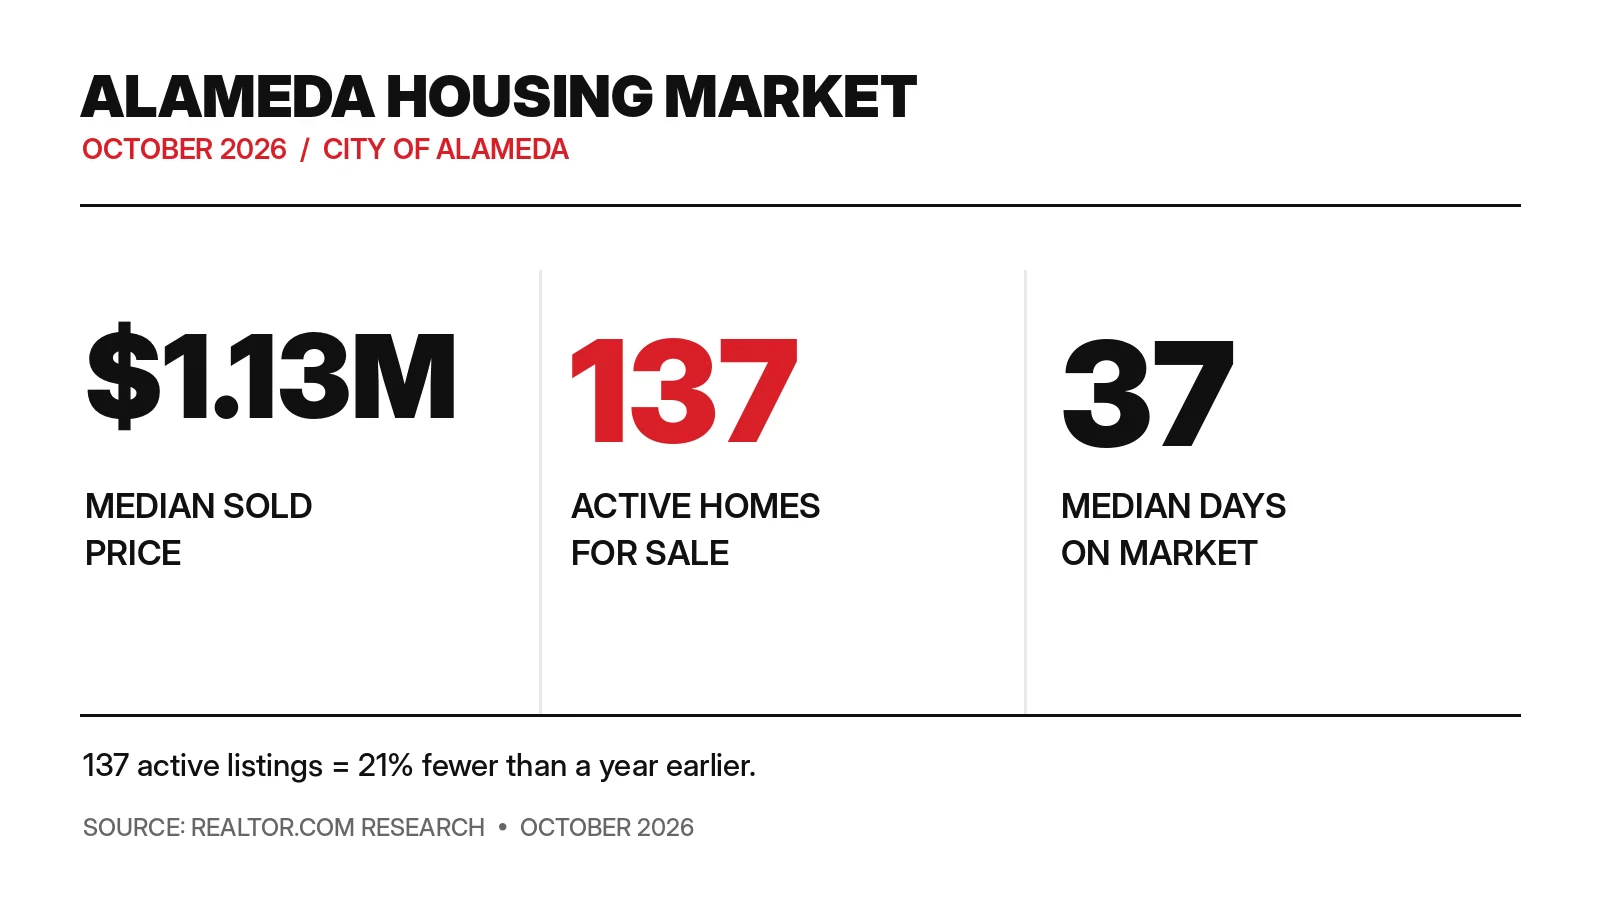
According to Freddie Mac's November 5, 2026 mortgage survey, the average 30-year fixed mortgage rate was **7.18%**, compared with **6.22%** a year earlier. Rates have moved down recently, but borrowing is still meaningfully more expensive than it was at the same time last year.Alameda home prices haven't simply fallen in response. [real estate agent.com](http://real estate agent.com)['s October 2026 city-level market report](https://www.real estate agent.com/local/market/california/alameda-county/alameda) shows:- **$1,134,900** median sold price.
- **137** active listings, about **21% fewer** than a year earlier.
- **37** median days on market for listings.
What higher rates actually do to a monthly payment
The rate sounds like a small percentage change. The monthly payment tells a different story.Here are two **illustrative** examples using a 30-year fixed mortgage, with the same purchase price and down payment in each year:ExampleAt 6.22%At 7.18%Monthly increase$800,000 home, 20% down ($640,000 loan)$3,928$4,336**+$408**$2,000,000 home, 40% down ($1,200,000 loan)$7,365$8,129**+$764**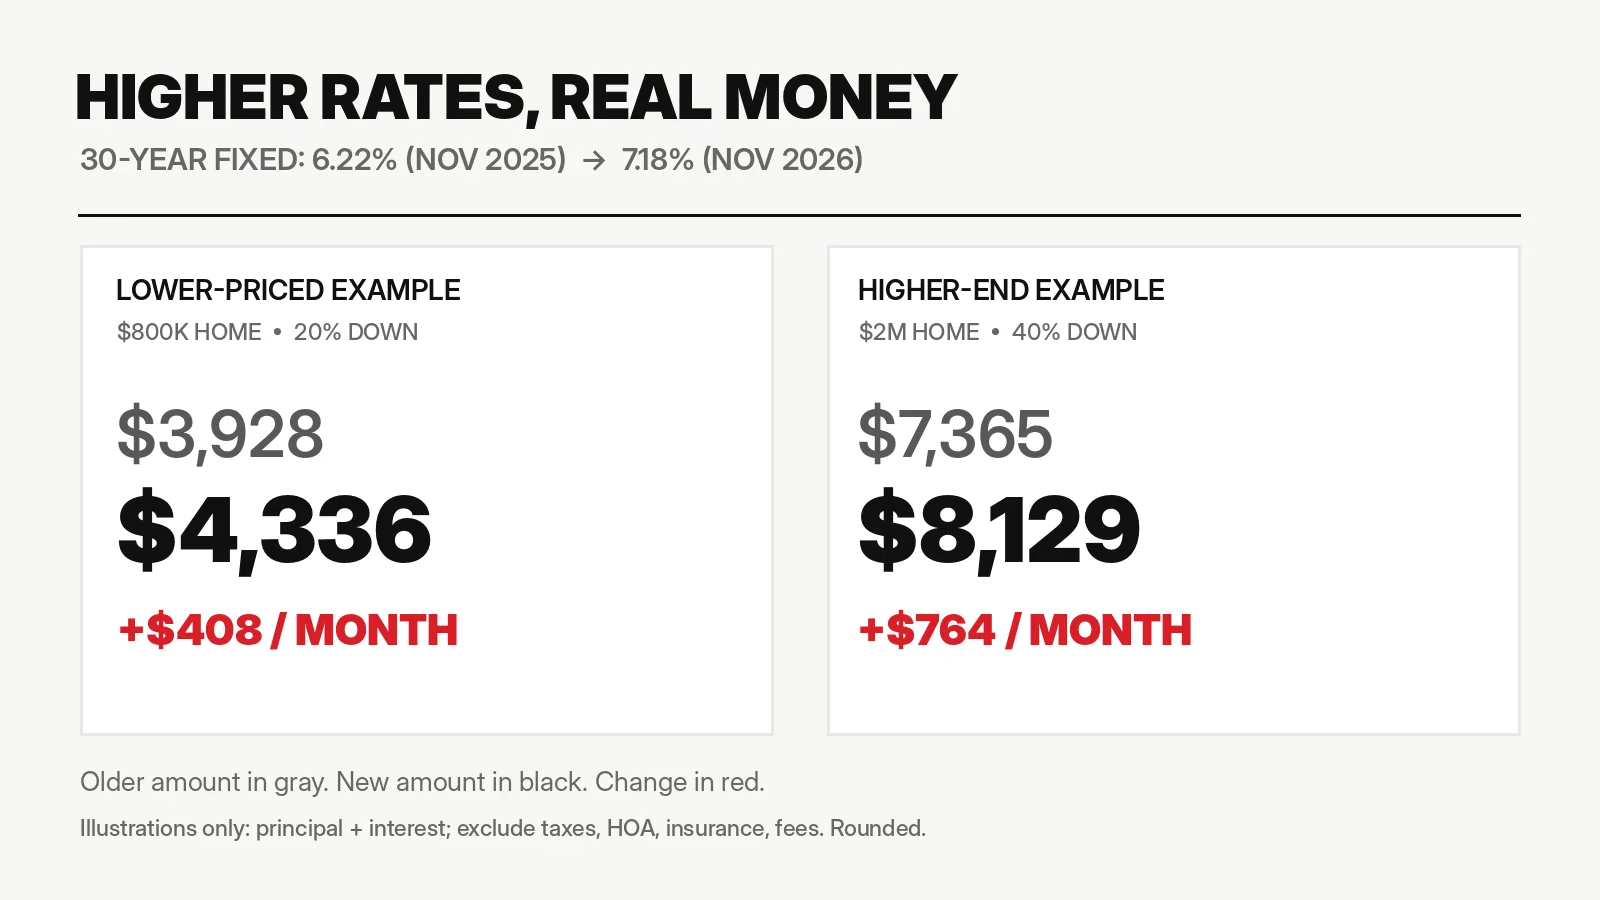
Lower-priced Alameda buyers are getting more payment-conscious
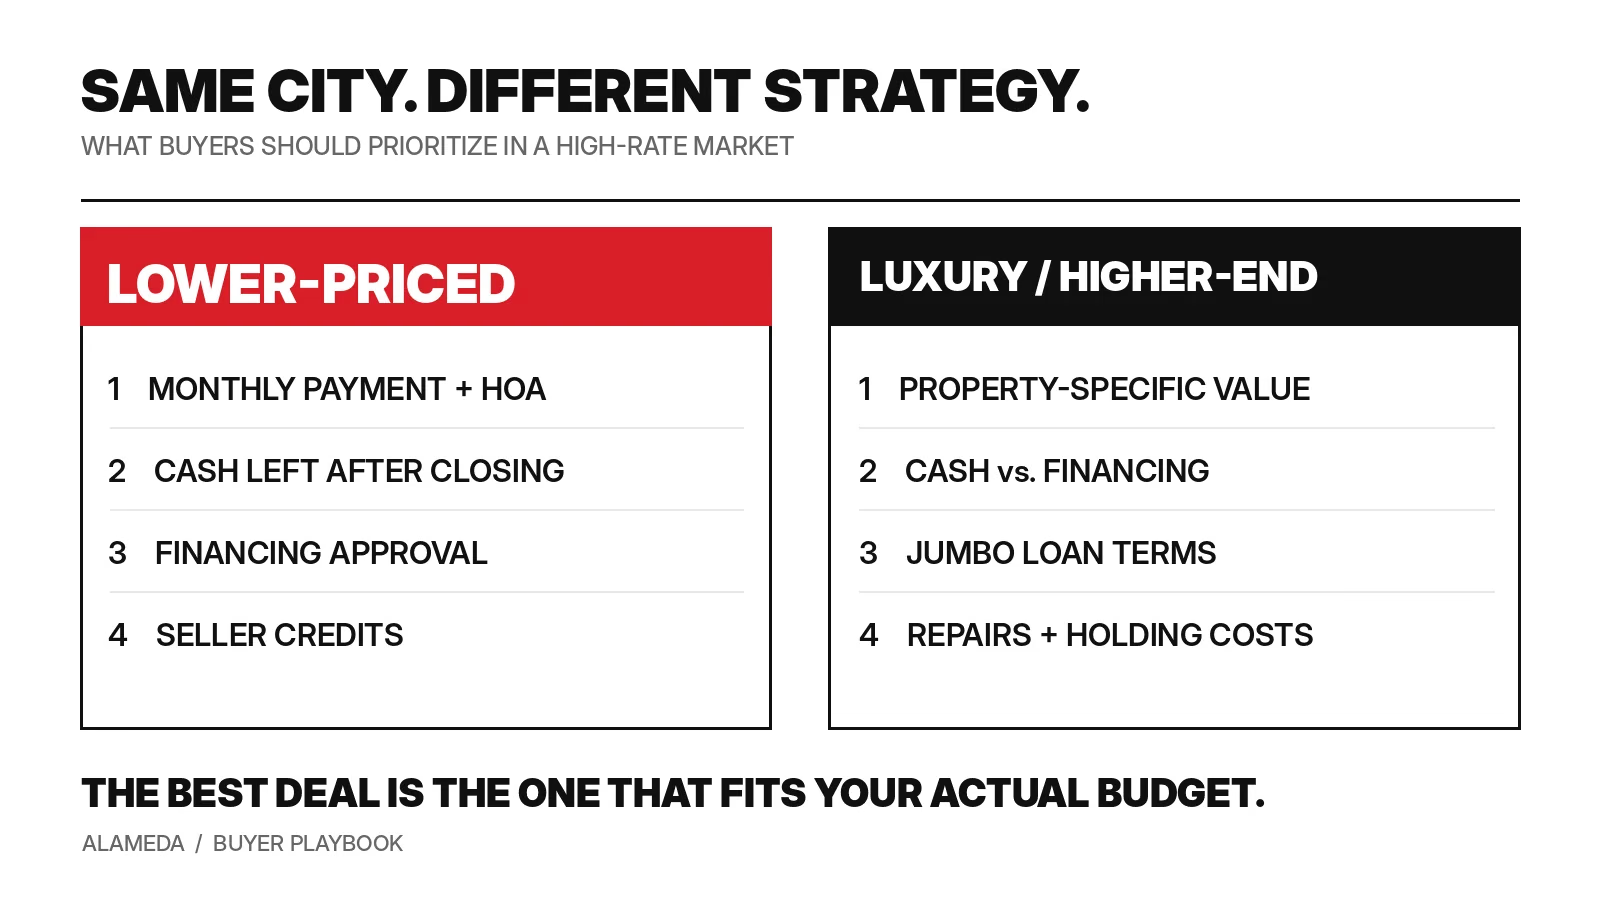
Let's be clear: "lower-priced" in Alameda doesn't necessarily mean inexpensive. Many buyers start by looking at condos, townhomes or smaller single-family homes because they're trying to find a way into the market without stretching their budget too far.For these buyers, the most important number often isn't the asking price. It's the **total monthly cost of owning the home**.A condo that's $100,000 less than a house may look like a better deal until you add a substantial HOA payment. Then there's property tax, homeowners insurance, utilities, and the cost of keeping some savings available after closing.I tell buyers to look at the full picture, not just the mortgage estimate. You don't want to win the house and then feel broke every month.Higher rates can also force some buyers to make a trade-off: smaller home, different neighborhood, more down payment, or a longer search.But there's a flip side. Buyers who are already approved and ready to move may have room to negotiate on homes that have been sitting, especially if a seller is more motivated than the listing price suggests.The key is **not confusing a lower asking price with a lower cost of ownership**.Luxury buyers are changing how they think about value
At the higher end, buyers are not immune to mortgage rates. Financing a large balance at today's rates still costs real money.The difference is that some luxury buyers can choose between a larger down payment, jumbo financing, selling another property first, or paying cash. Their biggest question may be less about getting approved and more about whether the property deserves the price.In Alameda, that matters because higher-priced homes aren't interchangeable.A distinctive historic home in the Gold Coast, a fully renovated East End property, and a larger home on Bay Farm Island appeal to buyers for different reasons.Layout, condition, outdoor space, location, parking, renovation quality, and long-term maintenance can matter more than a generic price-per-square-foot comparison.Higher rates may make some buyers more selective. If they're going to spend $2 million or more, they want the home to feel worth it.That doesn't guarantee huge discounts. A rare, beautifully presented home can still attract competition. A property that needs major work or is priced as if it's already remodeled may have a tougher time.**Luxury buyers are still buying. They're just less interested in paying a premium for a compromise.**An important financing detail for higher-priced homes
One detail many buyers miss: **a $2 million home doesn't automatically require a jumbo loan.** The loan amount matters, not just the purchase price.For 2026, the Federal Housing Finance Agency's one-unit conforming loan limit for Alameda County is **$1,249,125**.A buyer purchasing a $2 million home with 40% down would borrow $1.2 million, potentially staying within that conforming balance limit.A buyer putting 20% down on the same home would borrow $1.6 million and generally be shopping for jumbo financing.That can affect the loan programs, rates, documentation, and cash reserves a lender requires. I encourage higher-end buyers to compare real lender quotes before assuming a particular mortgage structure is best.A better negotiation might be about terms, not just price
Higher rates have made seller credits and financing terms worth a closer look.Take a hypothetical $800,000 purchase with 20% down. If the seller cuts the price by $20,000 and the buyer keeps putting 20% down, the financed balance falls by $16,000.At 7.18% over 30 years, that lowers principal and interest by only about **$108 a month**.That's not nothing. But sometimes a buyer benefits more from an allowable seller credit toward closing costs or mortgage discount points, depending on lender restrictions and the loan's actual pricing.The Consumer Financial Protection Bureau recommends comparing loan offers with and without points and looking at costs over the time you expect to keep the loan.There's no universal answer, and temporary buydowns should never be mistaken for permanent affordability.My approach is to run the numbers both ways. I'd rather negotiate something that improves the buyer's actual finances than celebrate a price reduction that barely changes the monthly payment.The Alameda buying strategy I'd use in this market
Frequently asked questions
Are higher mortgage rates making Alameda home prices fall?
Not across the board. Alameda's October 2026 median sold price was about $1.13 million, according to [real estate agent.com](http://real estate agent.com), even as mortgage rates remained elevated. Median prices also reflect which homes happened to sell, so individual properties need their own comparable-sales analysis.Are condos and townhomes easier to buy than single-family homes in Alameda?
They may have lower purchase prices, but not always lower total ownership costs. HOA dues, financing restrictions, insurance, and property condition need to be part of the comparison. Buyers should consider monthly payment and long-term expenses together.Do luxury homebuyers in Alameda still care about mortgage rates?
Absolutely. Even buyers with substantial equity may compare the cost of borrowing with the use of their cash. The difference is that higher-end buyers can sometimes structure the purchase with more flexibility.Should I wait for mortgage rates to drop before buying in Alameda?
I'd make the decision based on what you can comfortably afford now, the quality of the homes available, and how long you plan to own. Lower rates in the future are possible, but not guaranteed. Buying only makes sense if the current numbers work.The bottom line
The biggest change from higher mortgage rates isn't that people have stopped buying homes in Alameda. It's that they're asking tougher questions.Lower-priced buyers are spending more time on monthly affordability. Luxury buyers are spending more time on value, financing choices, and whether a home truly stands out.And both groups have less patience for a property that's overpriced or full of expensive surprises.**The best deal isn't automatically the cheapest home or the biggest price reduction. It's the home you can afford, at a price and on terms that make sense for you.**Sources and further reading
- Freddie Mac — Primary Mortgage Market Survey — November 5, 2026 mortgage rates.
- [real estate agent.com](http://real estate agent.com)[ — Alameda Housing Market](https://www.real estate agent.com/local/market/california/alameda-county/alameda) — October 2026 home prices, listings, and days on market.
- Federal Housing Finance Agency — 2026 Conforming Loan Limits — Alameda County's one-unit loan limit.
- Consumer Financial Protection Bureau — Comparing Loan Estimates — Evaluating rates and financing costs.
- Consumer Financial Protection Bureau — Mortgage Points and Credits — Comparing discount points and credits.
- Alameda County Auditor-Controller — Property Tax FAQs — Property assessments and supplemental tax bills.
Kenny Truong
Founder, #TeamFast
Area served: Alameda, CA, Berkeley, Alameda County, CA, Oakland, Alameda County, CA, Walnut Creek, Contra Costa County, CA, Oakland
Expertise: New Construction, Transit-Oriented Buyers, Multi-Family Investors, Condos, Divorce Sales