Why Summerlin West listings face steep price reductions
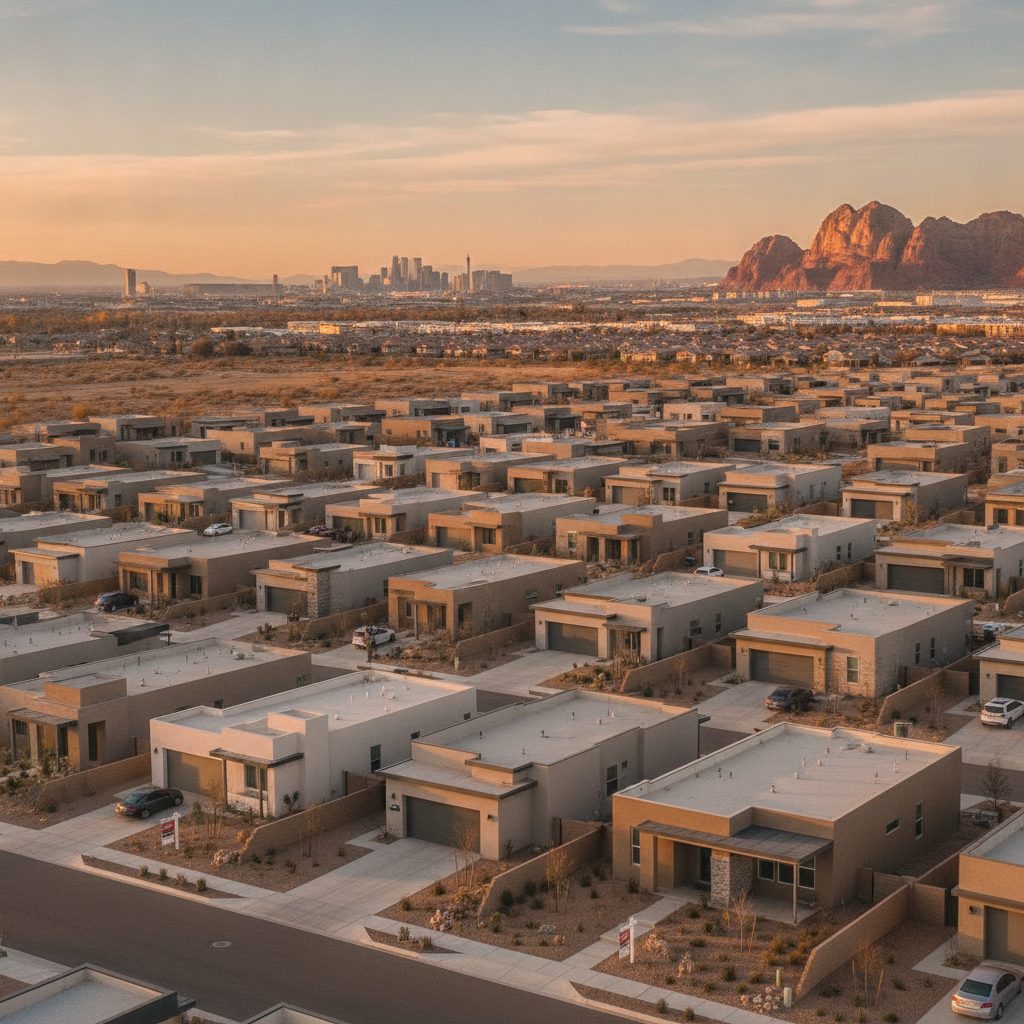
In Summerlin West, prestige alone no longer compels buyers to overlook mispriced square footage. Within the 89135 and 89138 ZIP codes bordering Red Rock Canyon National Conservation Area, 78 single-family homes closed in October at a median price of approximately $795,000. About 44 percent of those sales involved at least one formal price reduction prior to contract acceptance. Luxury purchasers operating along Desert Foothills Drive or near the Red Rock Country Club gates examine site orientation, finish durability, and required remodel expenses with close scrutiny.Enclaves like The Ridges continue to post transactions, but sellers who benchmark against 2022 peaks find their properties lingering on the MLS. A key factor unique to Summerlin villages is the compounding burden of master association assessments combined with Special Improvement District (SID) or Local Improvement District (LID) bond obligations. When a luxury listing asks $1.2 million with an unamortized LID assessment remaining on the parcel property tax bill, buyers in 89138 often negotiate to have the seller settle the remaining bond balance at closing or discount the baseline contract price accordingly.How Henderson resales compete with builder financing along Volunteer Boulevard
Across the southern rim of the valley, Henderson operates across distinct micro-environments: custom ridgeline properties, established suburban tracts, and master-planned expansion tracts. In MacDonald Highlands, positioned off Horizon Ridge Parkway, transactions depend on hillside sightlines toward the Las Vegas Strip, architectural uniqueness, and lot privacy. A buyer touring Dragon Ridge Drive rarely accepts production-grade tract finishes at custom square-foot pricing.A few miles south in Inspirada, existing homeowners face aggressive competition from corporate homebuilders. National production builders along Volunteer Boulevard and Via Inspirada frequently introduce promotional financing packages, temporary interest rate buydowns, and design center credits to move standing inventory. Resale sellers in Inspirada who list a three-year-old two-story home at market value must compete against new construction where builder-affiliated lenders offer financing incentives that lower monthly mortgage outlays. Resale sellers in Green Valley, by contrast, rely on mature street canopies, larger parcel setbacks, and the absence of ongoing special improvement district bonds to defend their listing numbers.Evaluating custom acreage in Section 10 against outer-ring master plans
Valuation practices diverge sharply when evaluating historic custom enclaves such as Section 10, located between Sahara Avenue and Desert Inn Road. Unlike master-planned communities governed by strict homeowner associations, Section 10 features half-acre and full-acre zoning, privately owned water wells, detached casitas, and equestrian zoning allowances. Derek Hoskins of The Hoskins Team at SERHANT. Las Vegas recently marketed a Section 10 estate featuring a nearly 29,000-square-foot lot, multigenerational living quarters, and private resort amenities.Pricing an unbranded custom compound requires an appraisal approach completely detached from suburban production subdivisions like Skye Canyon off US-95. In Skye Canyon, appraising a home is an exercise in matched-pair analysis using identical floor plans sold within 90 days inside the same development phase. In Section 10, comparable sales may sit miles apart across the central-west valley, requiring substantial manual adjustments for lot acreage, private septic systems, and accessory dwelling unit square footage.Why capital improvements fail to match appraisal sheets
A frequent friction point in Clark County transactions involves the gap between what an owner spent on property upgrades and what a licensed appraiser credits toward value. Sellers often expect an outdoor entertainment package or an imported interior slab to return full invested cost, but standard residential lending appraisal guidelines enforce strict bracket caps on mechanical and aesthetic additions.- Rooftop solar systems: A fully paid-off photovoltaic solar array reduces NV Energy utility bills, but appraisers in Clark County rarely award more than $10,000 to $15,000 in contributory value regardless of original hardware cost. Leased systems, by comparison, represent an ongoing payment liability that requires formal lease assumption, credit checks, and UCC financing statement filings during escrow.
- Custom swimming pools: Spending $120,000 on an infinity-edge pool and baja shelf in Centennial Hills will rarely increase an appraised valuation by more than $40,000 to $50,000, because the surrounding neighborhood price ceiling limits total valuation credit.